


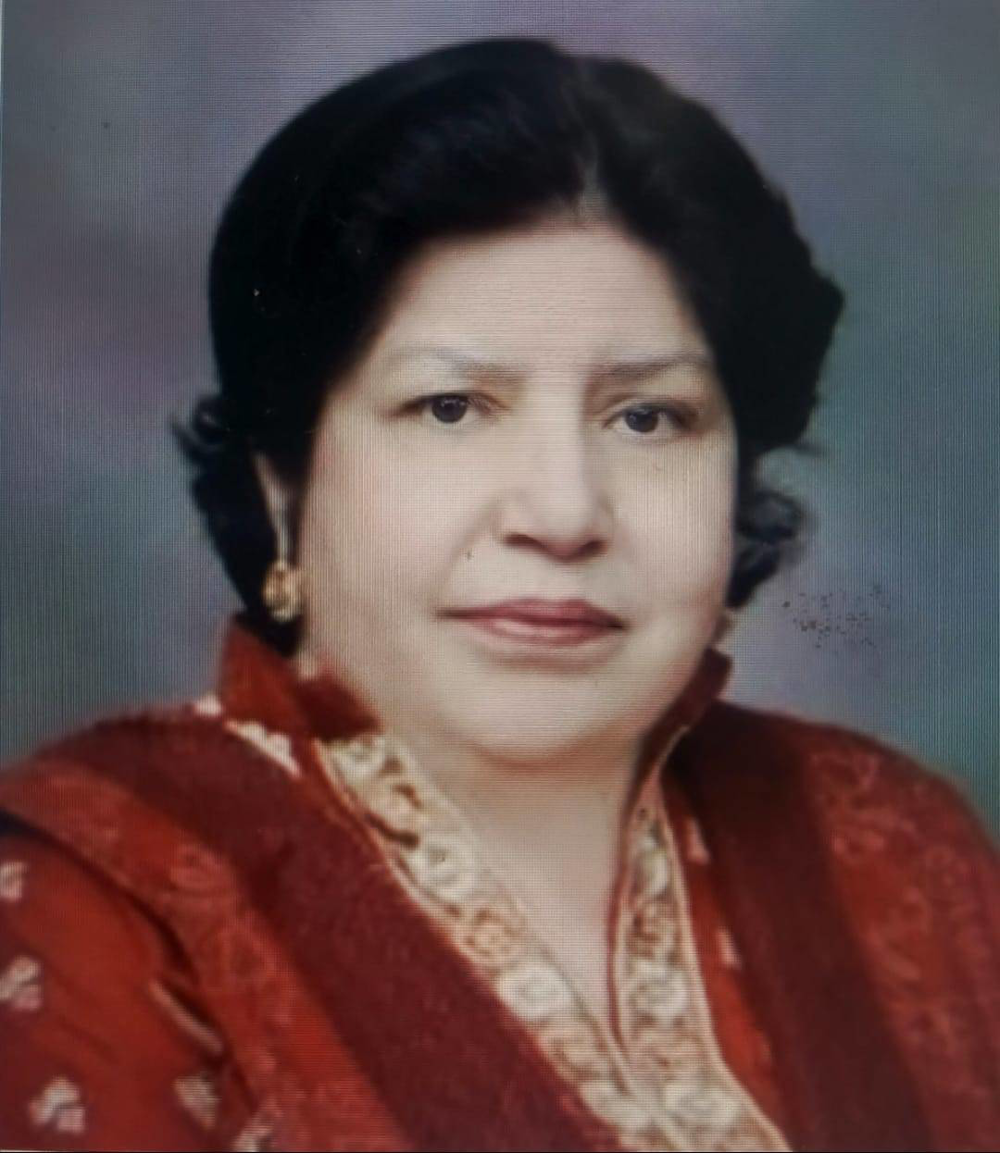
Professor Dr Saleha Naghmi Habibullah
Kinnaird College for Women, Lahore, Pakistan
saleha.habibullah@kinnaird.edu.pk
Improved Estimation of Parameters of Log-Symmetric Distributions for Achieving Better Fit
Abstract
Non-negative data arises in numerous fields. Self-inverse log-symmetric distributions provide an opportunity to construct estimators of distribution parameters that are more efficient than the corresponding well-known moment estimators, leading, in general, to more accurate modeling of non-negative real data. This paper presents a review of a number of self-inversion-based estimators that have been developed during the past ten to twelve years, and focuses on a self-inversion-based estimator of the rth moment about the mean. A simulation study is presented to demonstrate the superiority of the self-inversion-based estimator over the moment (MoM) estimator in terms of efficiency. The advantageousness of the self-inversion-based estimator over the moment estimator for purposes of modeling is demonstrated through application to two data-sets taken from the literature.
Keywords: self-inverse log-symmetric distributions, self-inversion-based estimators, simulation study, efficient estimator, modeling.